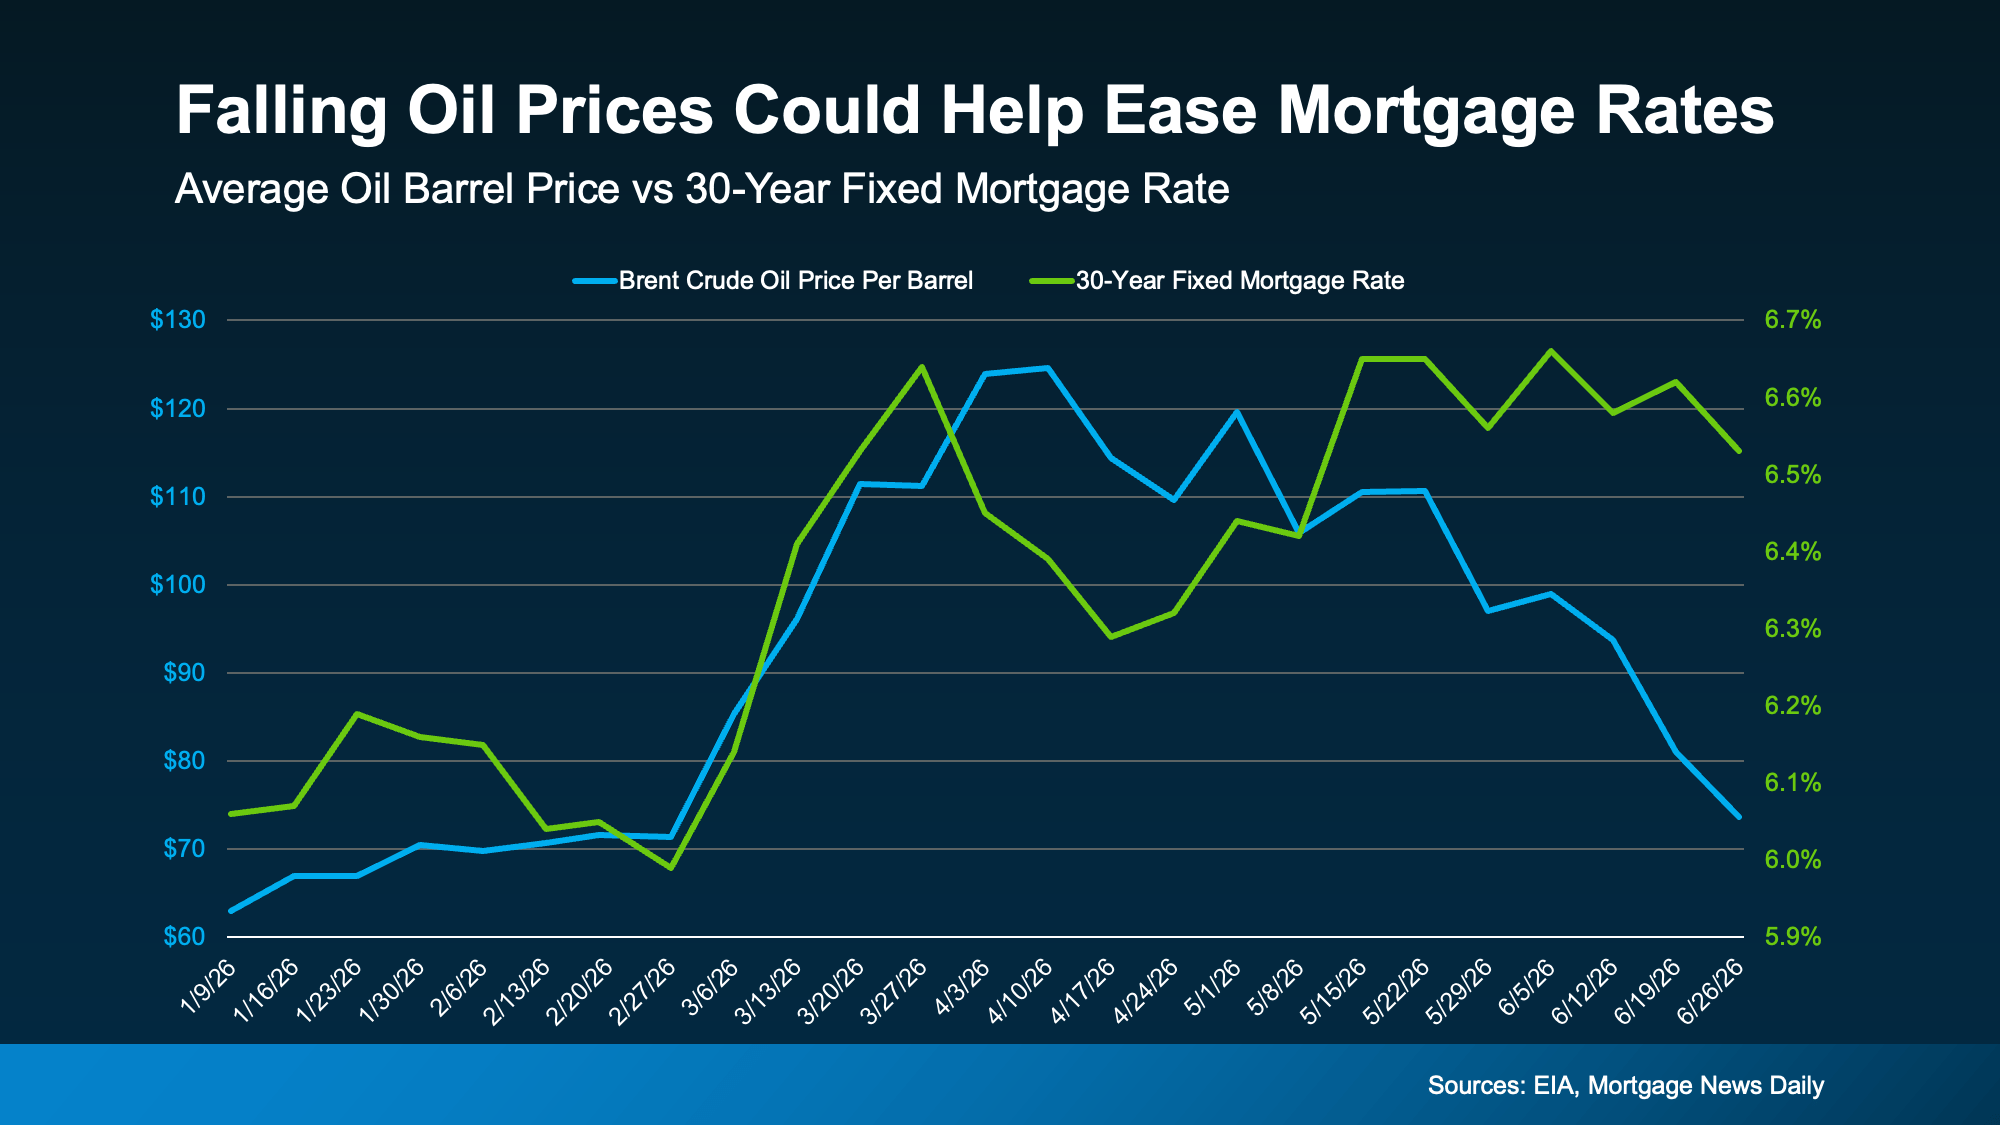Real Estate & Community News 


July 16, 2026

The Memphis Mid-Year Housing Market Report

Groome & Co. LLC Realtors® · Community Market Education

The Memphis Mid-Year
Housing Market Report

A plain-English look at what actually happened in our market through June 2026 — no hype, no spin, just the numbers and what they mean for you.

Freely shared with our community  •  Data: Memphis Area Association of REALTORS®, June 2026
The Headline Numbers

June 2026 at a Glance

$260,000
Median Sales Price
▲ 0.4% year-over-year
$314,986
Average Sales Price
▲ 4.7% year-over-year
3.4
Months of Supply
vs 2.8 a year ago
1,563
Pending Sales
A solid July pipeline

"Months of supply" = how long it would take to sell every home currently listed at the current sales pace. Under ~5 months generally favors sellers; over ~6 favors buyers. Memphis sits at 3.4 — still seller-leaning, but the most balanced we've been in two years.

The Big Picture

Is the Market Crashing? No — It's Normalizing.

You may have heard that home sales are down. That's true: the Memphis area recorded 6,942 sales in the first half of 2026, about 8% fewer than the same period last year. But here's what the headlines skip — prices rose at the same time. The median sale price climbed 4.5% to $230,000, and nearly $2 billion in homes still changed hands in six months.

In a true downturn, sales and prices fall together. What we have instead is a pickier market: fewer transactions, happening at higher prices, taking a reasonable ~49 days. That's a market returning to normal after several frenzied years — not one falling apart.

  2026 YTD 2025 YTD Change
Total Home Sales 6,942 7,532 ▼ 7.8%
Median Sales Price $230,000 $220,000 ▲ 4.5%
Average Sales Price $281,060 $270,052 ▲ 4.1%
Total Sales Volume $1.95 billion $2.03 billion ▼ 3.9%
New Home Sales (units) 339 384 ▼ 11.7%
Foreclosure Actions 239 267 ▼ 10.5%
The Supply Story

Buyers Finally Have Choices

3,5004,0004,5005,0005,067 — 24-month highJul-24SepNovJan-25MarMayJul-25SepNovJan-26MarMayJun-26

Active listings reached 5,067 in June — the highest level in at least two years, and 12.2% more than last June. For buyers, that means real selection and real negotiating room on terms, repairs, and closing help. For sellers, it means your home now has visible competition — pricing accurately from day one matters more than it has in years. Homes priced to the current market still sell in about 49 days; overpriced homes sit while the neighbors' sell.

Around the Area

How Our Communities Performed in June

Market June Sales YoY June Median YoY YTD Sales YTD Median
Fayette County 105 ▲ 61.5% $395,040 ▲ 6.8% 395 $376,990
Collierville 118 ▲ 3.5% $510,500 ▼ 6.8% 422 $504,500
Bartlett 155 ▼ 7.7% $282,000 ▲ 6.4% 719 $267,000
Germantown 85 ▼ 12.4% $485,000 ▲ 8.5% 346 $480,250
Millington 30 ▼ 11.8% $273,990 ▼ 9.3% 140 $261,495
Cordova 83 ▼ 18.6% $320,000 ▼ 2.9% 399 $305,000
Lakeland 35 ▼ 27.1% $425,000 ▼ 4.8% 139 $420,000
Arlington 21 ▼ 27.6% $575,000 ▲ 4.7% 114 $462,500

A note on reading this honestly: in smaller communities like Arlington (21 June sales) and Lakeland (35), one month is a tiny sample — a few closings either way swings the percentage wildly. Year-to-date columns are the more reliable trend. Arlington, for example, shows −27.6% for June yet its year-to-date sales are exactly flat with prices up 4.3% — a market short on homes to sell, not short on buyers.

Community Highlights

Three Stories Worth Knowing

Collierville & Germantown: two kinds of strength

Collierville was the only major suburb to sell more homes than last year (June and YTD), with new builds reaching a $992K median. Germantown sold fewer homes at notably higher prices — median up 8.5%, with custom new builds averaging $1.59M this year.

Affordability still exists

Millington's sales are up 15.7% this year with a $261K median and brand-new homes at $308K. Bartlett remains the metro's steadiest market — 719 sales, nearly identical to last year, at a $282K June median. First-time buyers: these are your markets.

What It Means for You

Practical Guidance, Whichever Side You're On

If you're thinking of selling

  • Values are still rising — the metro median is up 4.5% this year. Prepared sellers are doing well.
  • You have more competition than any month in two years. The first two weeks on market matter most.
  • Price to today's comparable sales, not your neighbor's 2024 result. Accurate pricing is what produces the ~49-day sale.
  • Presentation counts again: condition, photos, and readiness separate homes that move from homes that sit.

If you're thinking of buying

  • Selection is the best it's been in two years — 12% more homes to choose from than last June.
  • Use that leverage on terms: inspections, repairs, closing costs, rate buydowns — not on hoping prices collapse.
  • Prices rose while buyers waited: +4.5% metro-wide this year, +22% for existing homes in Fayette County.
  • New construction is friendlier than you think — builders are deliberately delivering smaller, more attainable homes, which is why new-home medians came down even as values held.

Every neighborhood is its own market. These are metro-level patterns — the right decision for your street depends on hyper-local data any good agent (ours or otherwise!) can pull for you.
GROOME & CO. LLC REALTORS®

Source: Memphis Area Association of REALTORS® June 2026 Home Sales Report (MAARdata — deed recordings in Shelby, Fayette & Tipton Counties, TN). Percentages compare June 2026 and January–June 2026 to the same 2025 periods. Small monthly samples in individual suburbs can swing sharply; year-to-date figures are the more reliable trend read.

We publish this report freely because an informed community makes better decisions — whether or not you ever work with us. Share it, question it, and ask us anything about your neighborhood. Boutique, independent, and Memphis-proud.

This report is general market education, not individualized advice. © 2026 Groome & Co. LLC Realtors®. Equal Housing Opportunity.

July 15, 2026

Think Nobody's Buying Homes Right Now? Think Again.

Think Nobody's Buying Homes Right Now? Think Again.


If you've been thinking about selling, you've probably seen plenty of headlines suggesting buyers have just about disappeared. But there's a big difference between a slow market and a stalled one.

Yes, mortgage rates are still higher than most people would like. Homes aren’t selling as fast as they were. And every week seems to bring another headline about buyers sitting on the sidelines. But here's what you haven't heard.

Despite everything going on, buyer demand has been remarkably resilient.

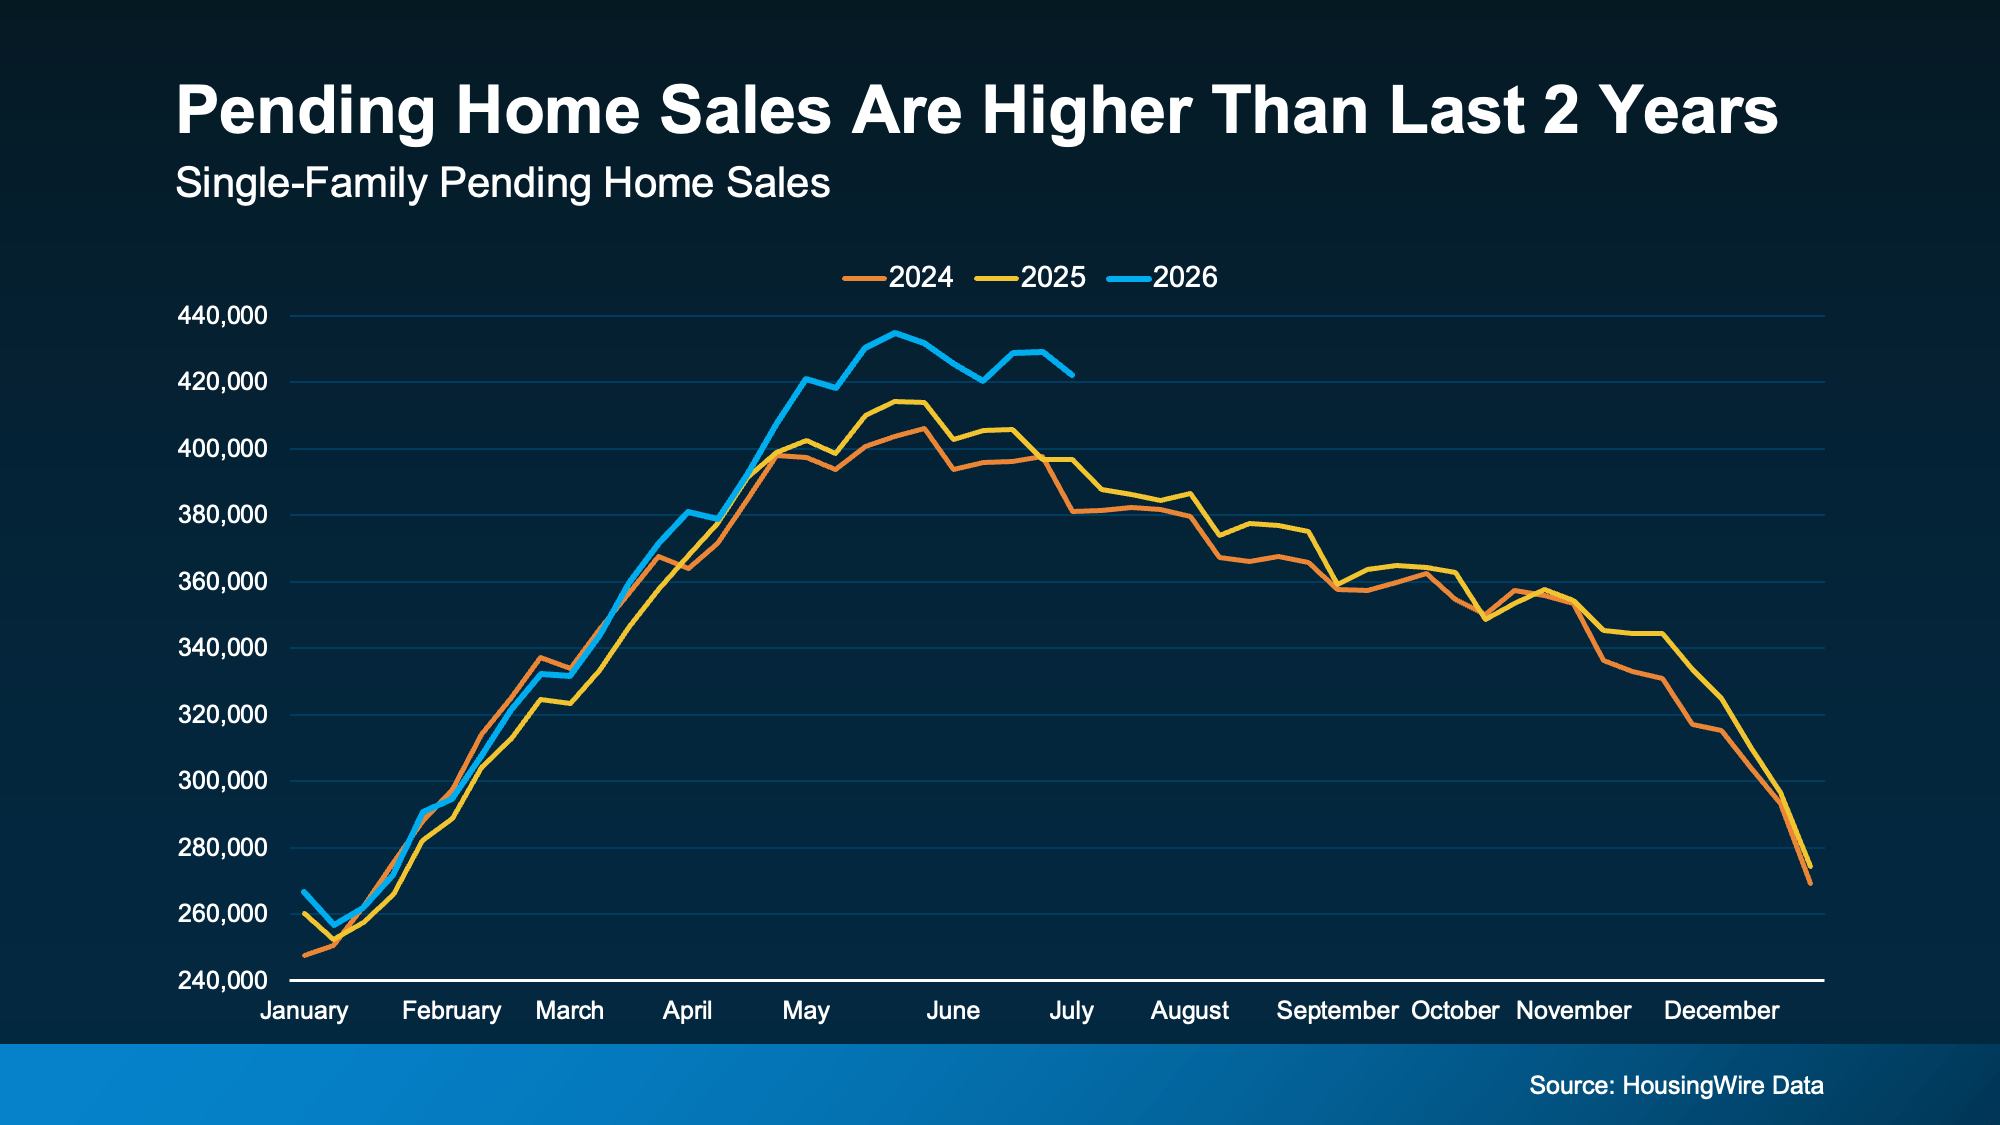
In fact, more sellers are getting to put up the “pending sale” sign now than during the last two years. What's even more surprising is that they're doing it at a time of year when activity usually starts to slow down.

And if you're thinking about selling, that's a trend worth paying attention to.

Buyers Are More Active Than You Think

One of the best ways to measure buyer demand is by looking at pending home sales. Those are homes that have gone under contract but haven't closed yet. Think of them as a real-time pulse check on the market and whether buyers are still buying.

HousingWire Data shows more homes are going under contract than at the same time the past 2 years (see graph below):

a graph showing the sales of a home sales

While it may come as a surprise, the numbers speak for themselves. It doesn’t mean buyers are everywhere, but it does mean they’re still active right now. And even if this ebbs and flows a bit in the weeks ahead, right now we’re still ahead of where we’ve been lately. That's encouraging news if you're thinking about selling because it tells us something important…

People haven't stopped buying homes. Serious buyers are still making moves.

And a lot of these people are buying because they decided they can't keep waiting. Whether it's a growing family, a new job, retirement, or simply wanting a different home, life keeps moving… even when mortgage rates stay higher than we'd like. As Lawrence Yun, Chief Economist at the National Association of Realtors (NAR), explains:

“A late spring buyer rush—even with mortgage rates not budging—is an indication of pent-up housing demand and consumers’ acceptance of above-6% mortgage rates as the new normal."

So, if you've been worried no one’s buying, this data should give you some confidence. Today’s buyers aren't just casually browsing open houses on a Sunday afternoon, they've spent months waiting for rates to improve and now they realize they can’t wait anymore.

That means they have a purposeand a timeline. And that's exactly the kind of motivated buyer you want to work with.

What This Means for Your Sale

Does that mean every house will sell instantly? No.

Today's market is more balanced than it was a few years ago.  So, you can’t just price your house however you want or skip preparing it for the market.

Now buyers have choices, and they're willing to wait for the right home at the right price. But sellers who understand today's market (and price and position their homes right) are still finding success. Because the idea that "no one's buying right now" just isn't supported by the data.

The buyers are there.

The opportunity is there.

The key is having the right strategy to capture it.

Bottom Line

This year's housing market may be moving slower than many of us hoped. But, buyer demand is more resilient than the headlines suggest.

If you're wondering whether there are enough buyers for your house, let's connect. I'll show you what's happening in our local market and build a strategy that helps you take advantage of the momentum that's already here.

July 14, 2026

Student Loans Are Back in the News. Don't Let It Put Your Homeownership Plans on Hold.

Student Loans Are Back in the News. Don't Let It Put Your Homeownership Plans on Hold.


Student loans are back in the spotlight. And whether you've been following the headlines closely or just catching bits and pieces here and there, there's a good chance they've been on your mind lately.

And if you’re questioning whether you have to hit pause on your plans to buy a home, here's the thing you have to remember:

Having student loans doesn't automatically mean buying a home has to wait.

The Biggest Myth About Student Loans and Buying a Home

One of the most common misconceptions among first-time buyers is that they have to pay off their student loans before they can qualify for a mortgage. But in most cases, that's just not true. 

As an article from Redfin explains, student loans usually get evaluated the same way other debts do, like credit cards or car payments:

“Yes, you can get a mortgage with student loan debt. Lenders primarily assess your debt-to-income (DTI) ratio, which compares your monthly debt payments, including student loans, to your gross monthly income. Having student debt doesn’t automatically disqualify you if your DTI is within acceptable limits.”

So having that loan on your credit report isn't some special red flag that immediately disqualifies you.

Instead, lenders look at your overall financial situation, including your income, credit history, and more. Student loans are one piece of that puzzle, but they’re not the entire picture.

You're in Better Company Than You Think

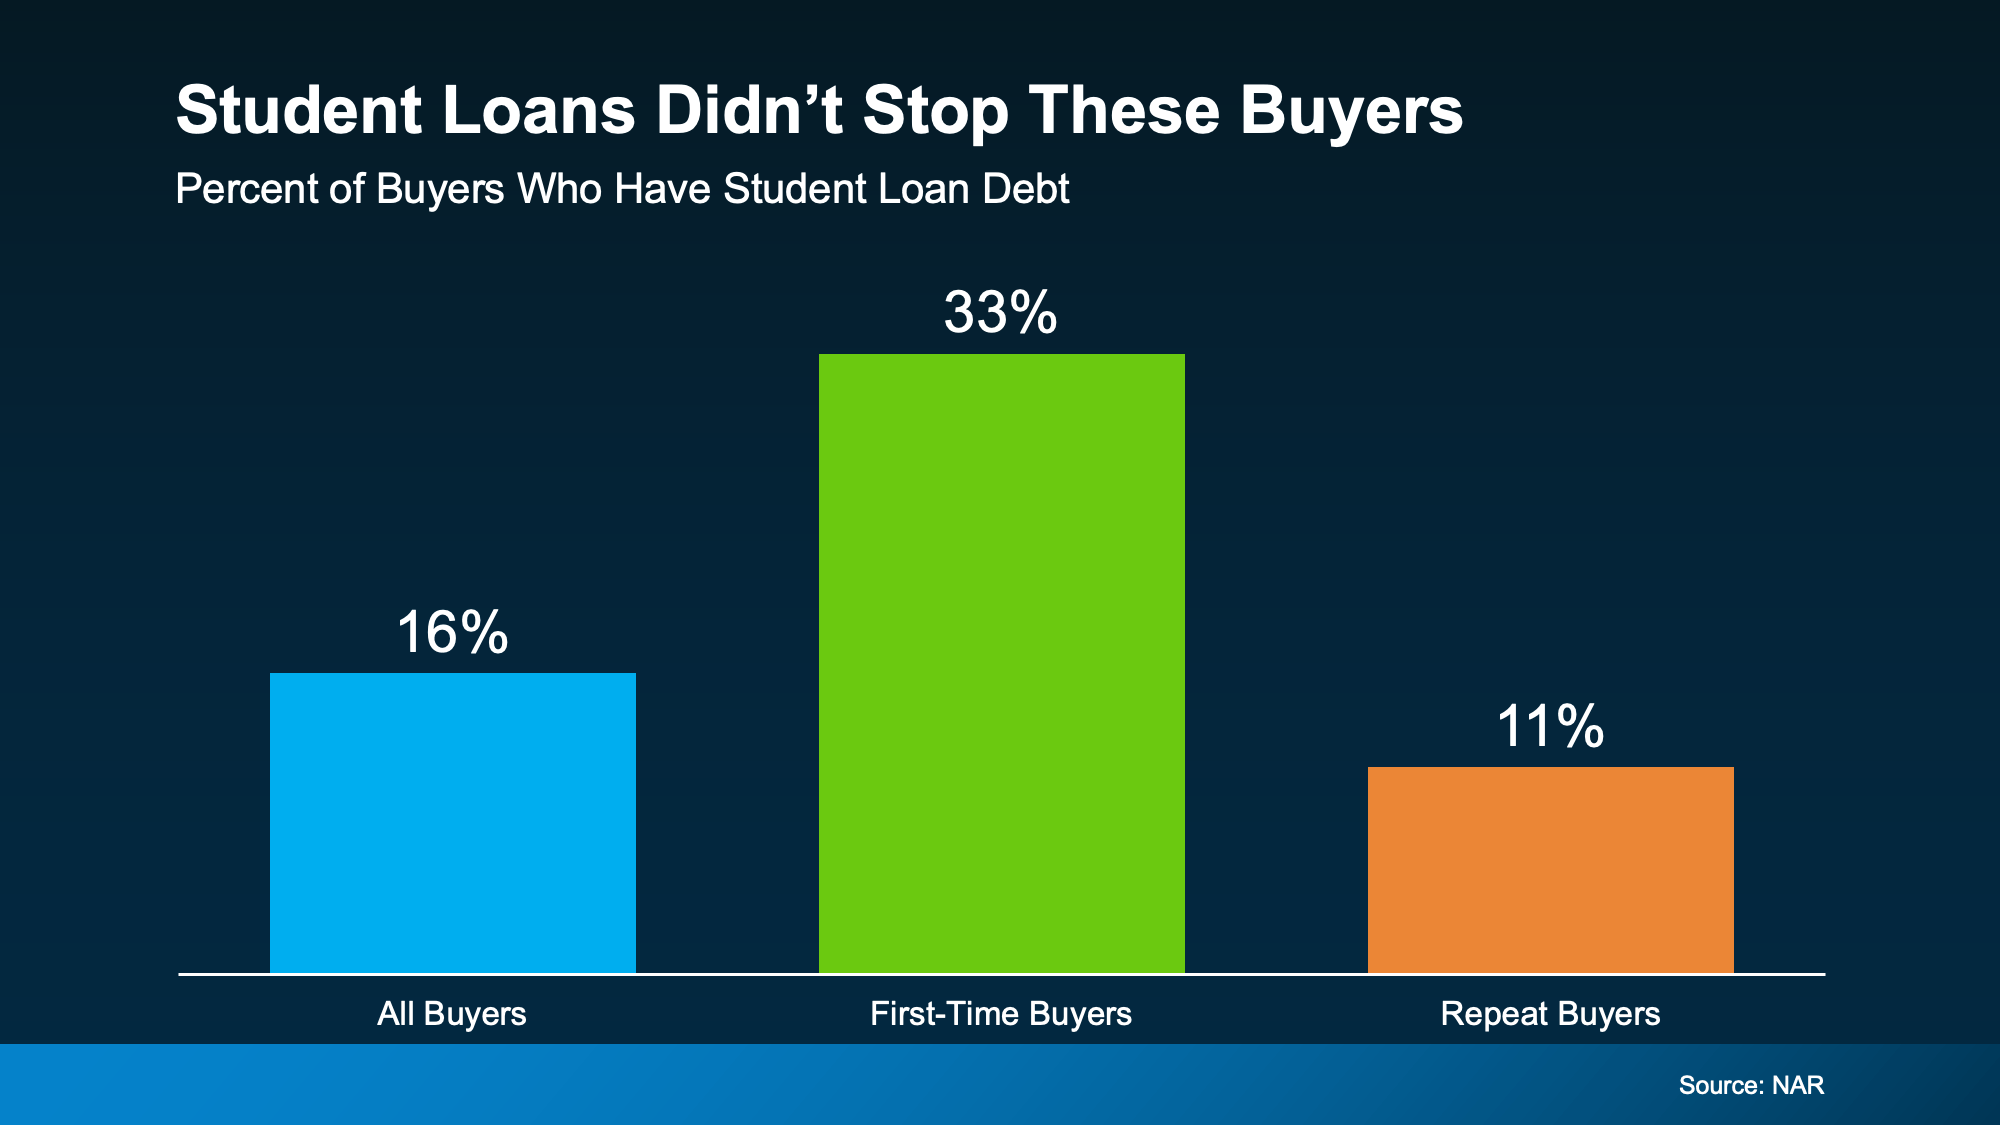
Just to really drive this home, here’s a stat from the National Association of Realtors (NAR) that proves you can have student debt and still buy a home. Their research shows 33% of first-time homebuyers still had student loan debt.

a graph of a student loan debt

That's 1 out of every 3 first-time buyers. The median amount they owed? $30,400.

Let that reassure you that people are buying homes with student debt every day. And carrying student loans doesn't automatically put homeownership out of reach.

Don’t Count Yourself Out Before You Even Try

At the end of the day, here's where a lot of buyers trip themselves up. They assume the worst and never even check what they could actually qualify for. But your situation is more unique than a blanket "no."

If your income is steady and the rest of your finances are in decent shape, buying a home could be more realistic than you think. The only way to know for sure is to actually run the numbers with someone who does this for a living.

You may discover you're closer to buying than you think.

Bottom Line

Student loans don't have to be the thing standing between you and owning a home. If you've been putting off your homebuying plans because of that debt, talk to a lender about your options. It may not be the barrier you think it is.

July 13, 2026

The “Take It or Leave It” Attitude Is Fading from the Market – What That Means for You

The “Take It or Leave It” Attitude Is Fading from the Market – What That Means for You


Negotiations are back. More buyers are asking for better deals, and more sellers are giving them. Builders are throwing in extras, too. 

That’s why whether you’re buying or selling today, there are two terms you’ll hear a lot: concession and incentive.

  • A concession is something a seller agrees to during negotiations to get a deal done.

  • An incentive is a perk a builder (or a seller) advertises upfront to attract buyers.

Let’s run through what you need to know about both and how they could play a role in your move.

More Sellers Are Agreeing to Concessions

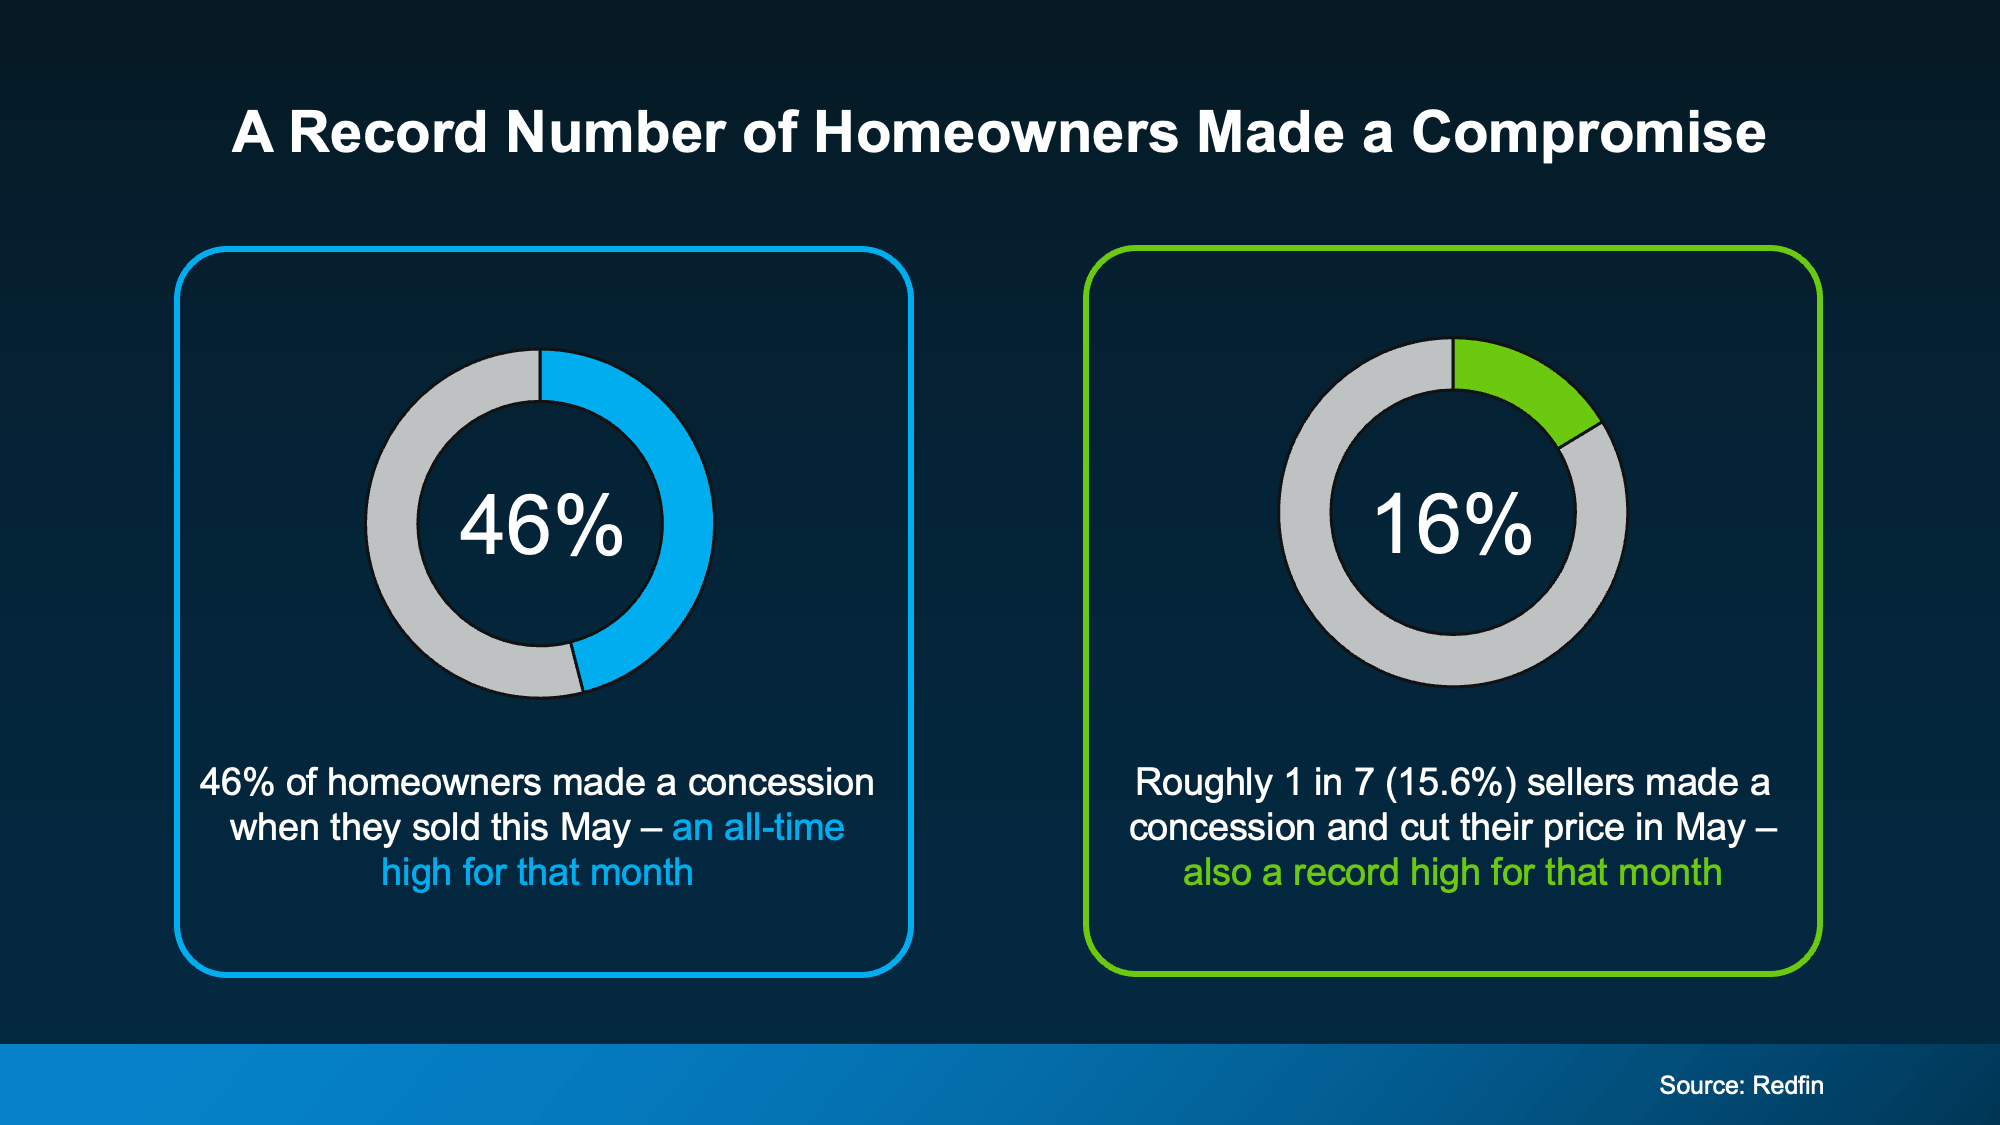
Almost half (46%) of homeowners who sold recently gave the buyer a concession, according to Redfin. That’s the highest share on record for this time of year. And roughly 1 in 7 (16%) sellers went a step further, cutting their asking price and offering a concession on top (see chart below):

a diagram of a homeowner's market 

So, what kind of concessions are we talking about?

A seller might cover part of your closing costs, take care of a repair, or offer a credit that trims your upfront costs. It’s how they keep a deal on track when buyers have more options to choose from – and homeowners aren’t the only ones compromising.

Builders Are Cutting Prices, Too

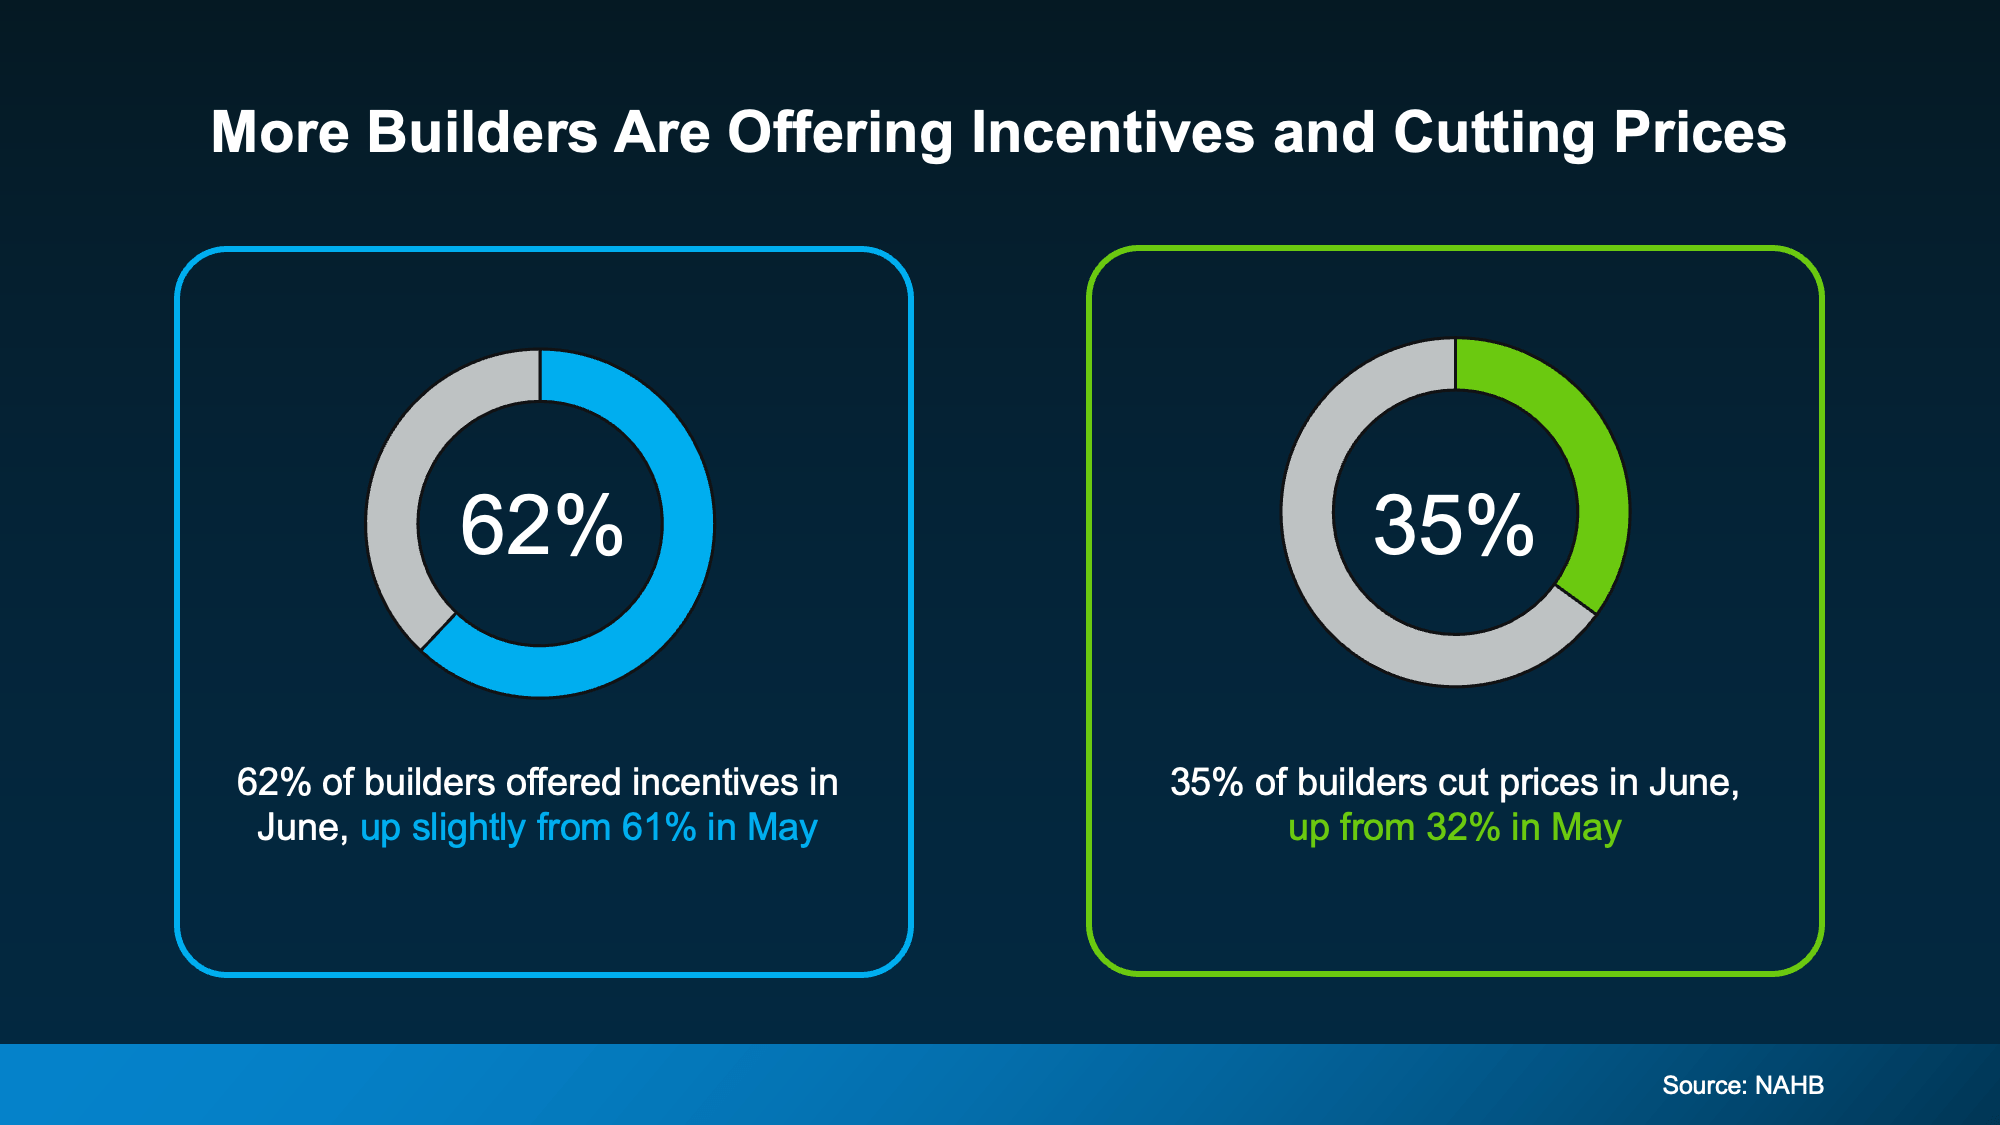
Newly built homes are seeing the same push and pull. According to the National Association of Home Builders (NAHB), 62% of builders are offering incentives right now. And about 35% are cutting prices outright (see chart below):

a screenshot of a graph

Those incentives often look like:

  • Price adjustments

  • Mortgage rate buydowns

  • Free upgrades, like nicer finishes or appliances

Danielle Hale, Chief Economist at Realtor.com, explains why:

"New construction has been one of the steadiest parts of the housing market over the past few years, but builders are clearly responding to today's affordability pressures and higher levels of existing-home inventory."

Even builders, who many people think rarely negotiate, are competing on price and perks. They have been for over a year now. The same data shows this is the 15th straight month where more than 60% of builders have offered incentives to sweeten the deal. And that’s significant.

What This Means for Your Move

If you're buying, this is a good time to ask. Whether you have your eye on an existing house or a newly built home, there's a chance the seller or builder will meet you partway on price, terms, or both.

If you're selling, expect buyers to ask. Even builders of brand-new homes are making concessions more often than not right now. Holding firm on every term could mean more time on the market, or a lost sale altogether.

Bottom Line

Sellers and builders are both giving buyers more to work with this year. Want to know what’s realistic to expect in concessions and incentives in our market? Let’s connect.

July 9, 2026

What To Expect from the Housing Market in the Second Half of 2026

What To Expect from the Housing Market in the Second Half of 2026


If the first half of this year has left you feeling stuck, you're not the only one. Mortgage rates stayed higher than people wanted. Affordability remained tight. And uncertainty overseas added another layer of pressure nobody saw coming.

That's why so many people are asking the same question: Will the second half of the year be any better for the housing market?

While nobody has a crystal ball, there are a few encouraging signs things could start moving in a better direction. Here's what to watch.

Mortgage Rates Could Be Near a Turning Point 

One of the biggest reasons mortgage rates haven't come down yet is inflation. And higher energy prices and uncertainty overseas are at least part of the reason inflation is still elevated. The encouraging news?

Oil prices have already started coming back down.

That may not sound like it has much to do with buying a home. But historically, mortgage rates and oil prices tend to move in the same direction.

Take a look at the graph below. Generally, they rise and fall together. Both went up in February when the conflict began. While there’s been some volatility lately, experts at the U.S. Energy Information Administration (EIA) say oil prices are forecast to come down. And since oil prices have been on an overall downward trend lately, mortgage rates could come down too:

a graph showing the price of a mortgage rate

It's too soon to say exactly when that will happen (or by how much they’ll fall), but if energy prices go down, inflation cools off, and tensions overseas ease, mortgage rates could come down in the second half of the year.

And that’s good news for anyone thinking about moving. The first half of the year tested everyone's patience. The second half may finally reward it.

Home Prices Could Pick Back Up

A lot of people want home prices to fall too. But that’s not what most forecasts show.

While price trends are going to vary by area, and some places are seeing mild declines, experts still expect home prices to net positive this year at the national level.

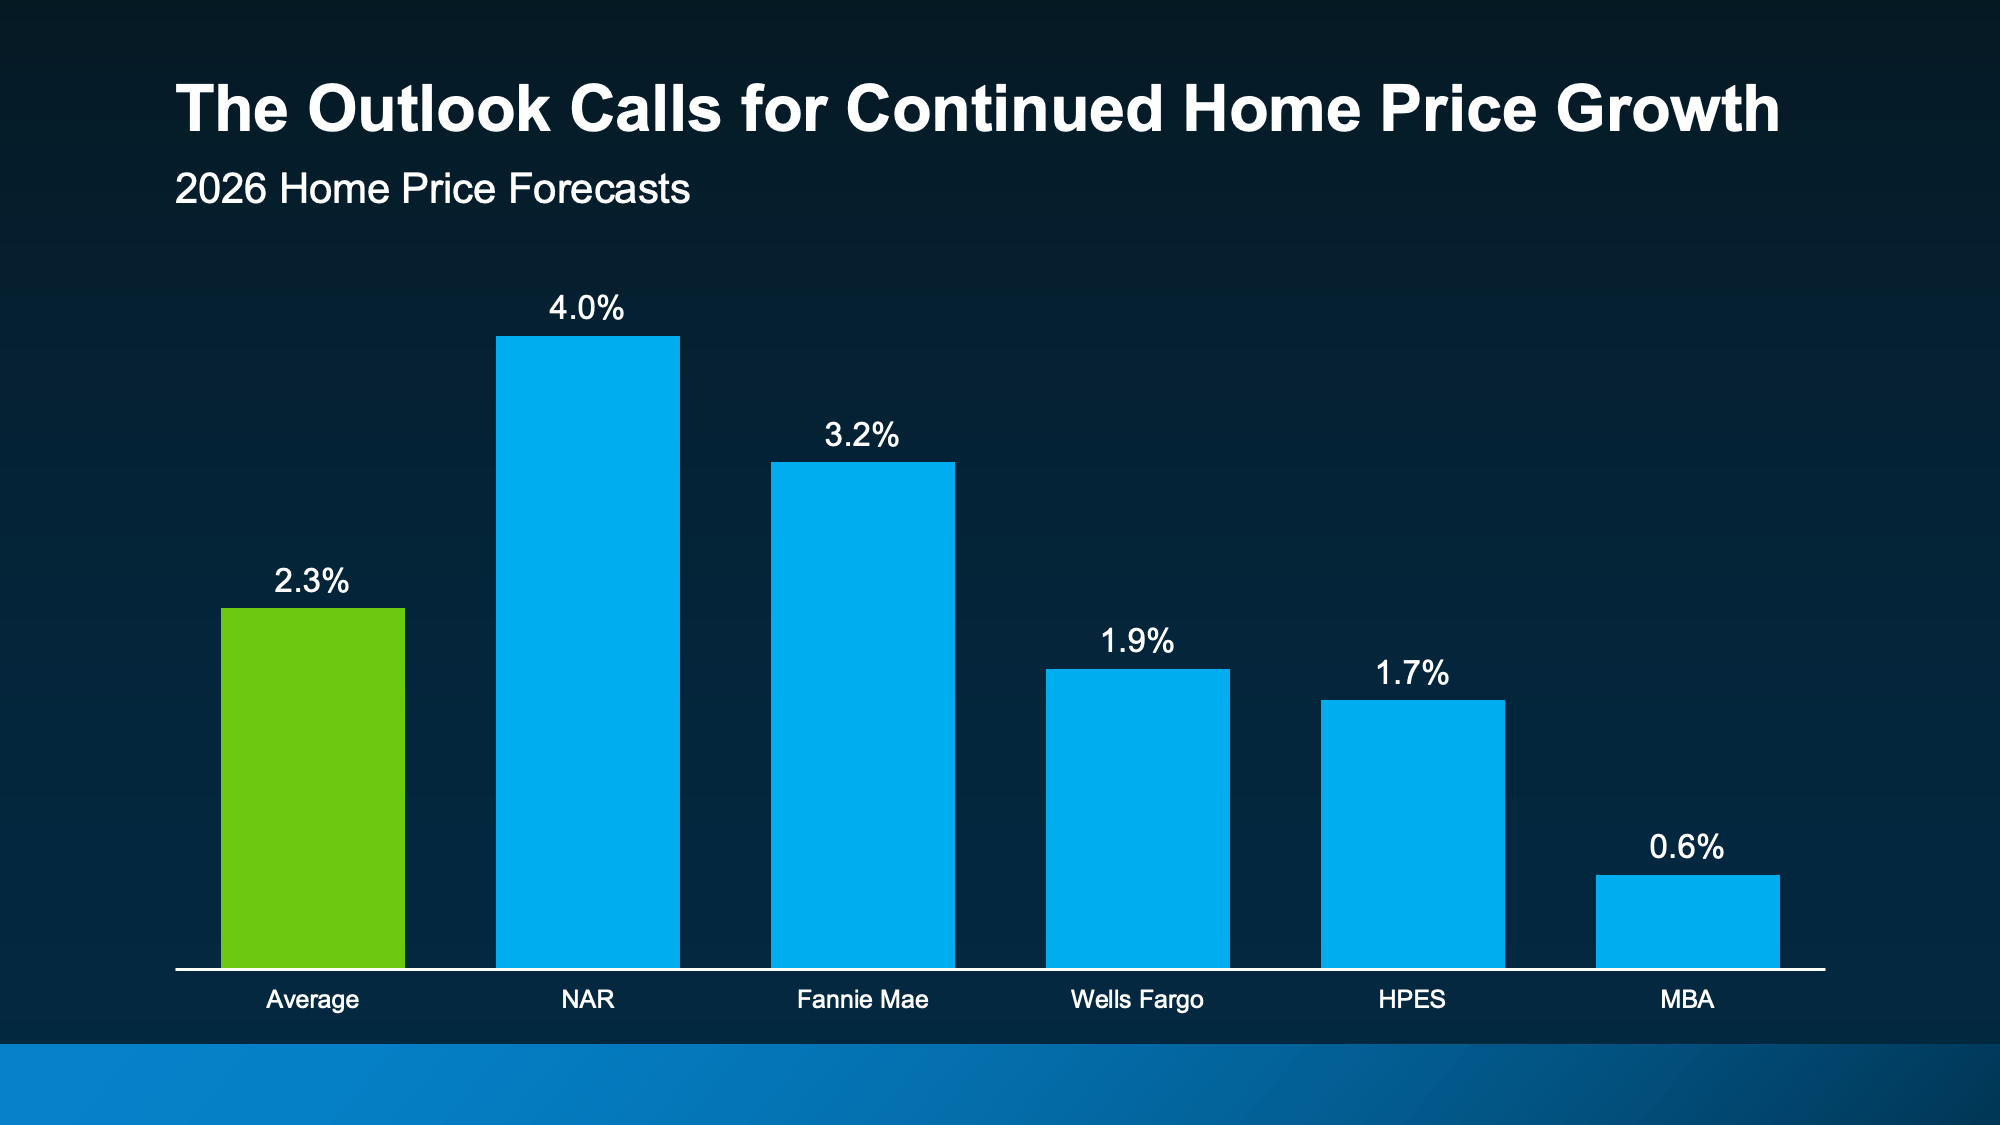
In fact, they’re projecting prices will rise by an average of 2.3% in 2026 (see graph below):

a graph of blue rectangular objects

What does that mean for you? Right now, Federal Housing Finance Agency (FHFA)data shows prices are up about 1.7% nationally year-over-year. The average forecast for all of 2026? 2.3%.

Based on those projections, home price growth would have to pick up a bit during the second half of the year. Nothing dramatic, just enough to finish the year around that projected 2.3% gain.

Here’s why that’s possible.

The number of homes for sale has grown, but that growth may be starting to slow down. And if rates improve, more buyers could jump back into the market. More buyers competing could put modest upward pressure on prices, especially if inventory’s not growing as fast.

That’s why buyers shouldn’t assume waiting will guarantee a lower price later. And for sellers, that’s great news if you’ve been worried about your home’s value.

More Homes Are Expected To Sell

If you've been wondering why the housing market has felt quieter lately, you're not imagining it. Home sales have been slower than many experts expected. But that doesn't mean people have stopped wanting to move.

A lot of people still want or need to make a change. They’ve just been waiting for more certainty, better affordability, or a clearer read on where the market is headed. And early signs show that may be on the horizon. 

If rates ease and confidence improves, more people may finally move. As Odeta Kushi, Deputy Chief Economist at First American, explains:

“Overall, we expect pent-up demand to continue emerging gradually. But the pace of recovery will vary significantly across markets and will depend on the path of rates, labor market conditions and inventory growth.” 

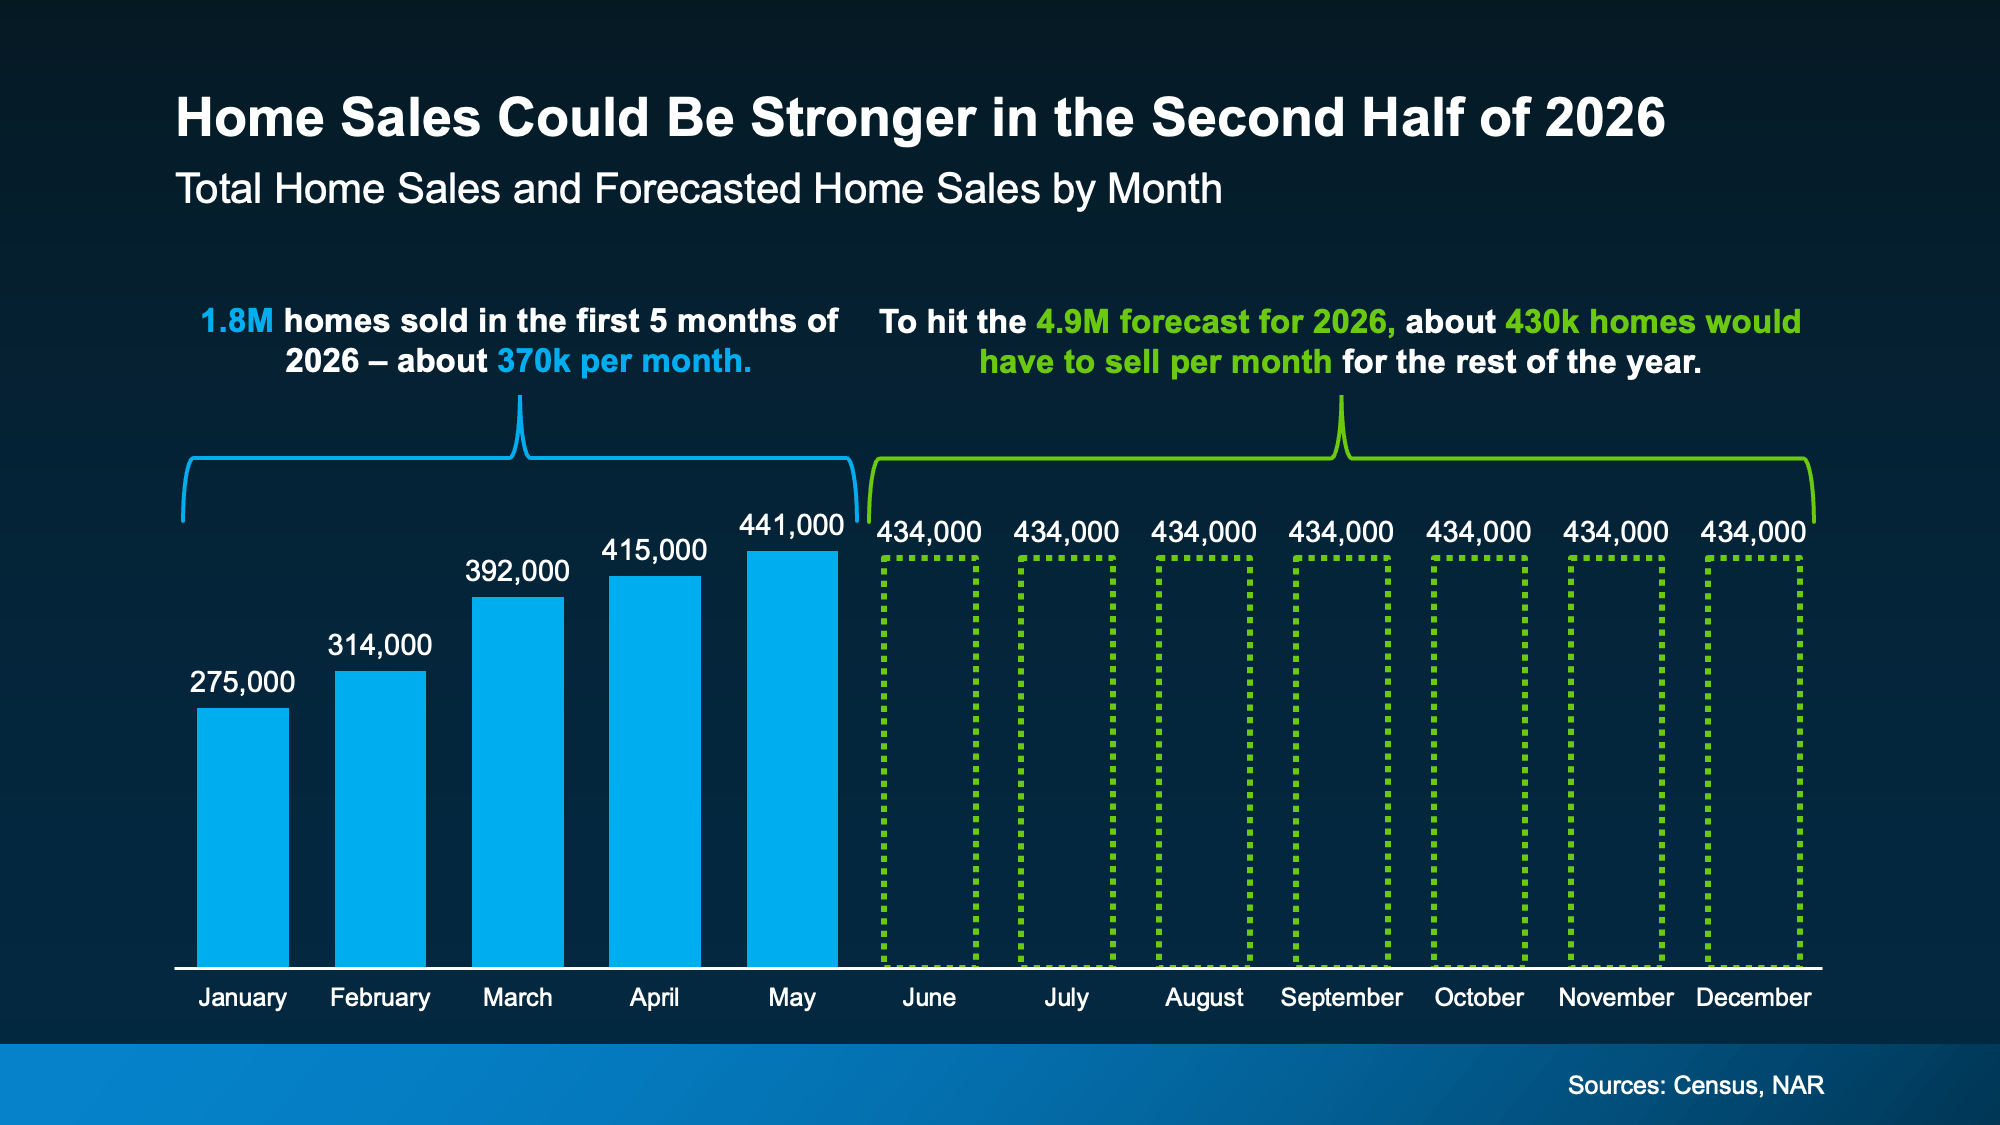
Based on the latest forecasts, to hit the number of sales expected this year, here’s what would have to happen. The second half of the year would need to outperform the first in sales (see graph below):

a graph of sales and statistics

In fact, each month for the rest of 2026 would have to come close to matching the best month we've had so far this year (May). That’s a sign the experts are calling for more momentum headed into the second half.

More people will finally make their move happen – and you've got the chance to be one of them.

Bottom Line

The second half of the year probably won't be perfect. But it could be better.

Mortgage rates may ease. Home sales could pick up. And prices are expected to continue rising at a healthier, more sustainable pace. If you've been waiting for signs of progress, this is it.

If you want to understand what these forecasts mean for your plans and what’s happening in our local market, let’s connect.

July 8, 2026

Oakland TN's Summer 2026 Buyer's Market Is Here

Posted in Blog history
July 7, 2026

Oakland TN Housing Market 2026: Is Inventory Balancing?

Posted in Blog history
July 1, 2026

Oakland TN's 2026 Buyer Shift: Where Prices Stand Now

Posted in Blog history
June 29, 2026

Mid-6% Mortgage Rates: A 2026 Buyer's Guide for Oakland TN

Posted in Blog history
June 28, 2026

Buying in Oakland TN: Reading the 2026 Market Shift

Posted in Blog history